Why Would Someone Choose Privacy Over Rate for a Watch-Backed Loan?
It is Thursday evening in Scottsdale. Barrett-Jackson is underway at WestWorld of Scottsdale, a car you have been watching is coming up soon, and the money you want to use is tied up elsewhere. You could apply for a bank line of credit, sell an asset, or borrow against a watch you already own.
That last choice can make sense when timing and discretion matter more than getting the lowest possible rate. It is not automatically the cheapest choice, and it is not right for everyone. But for some owners, a watch-backed loan offers short-term liquidity without forcing a sale or putting a broader financial request through a conventional lending process.
The decision is best understood as a tradeoff: what does speed and privacy cost, and what does waiting, disclosing more information, or selling the watch cost instead?
What a Watch-Backed Loan Is—and Is Not
A watch-backed loan is an asset-backed loan. The watch serves as collateral, and the lender assesses its identity, condition, marketability, and value before making an offer. If the borrower accepts, the watch is held according to the lender’s custody and loan terms while the borrower receives funds. Repayment terms, fees, interest, and what happens if the loan is not repaid should all be clear before signing.
This is different from a bank line of credit. A bank line is a credit product based on the borrower’s financial profile and the bank’s underwriting rules. It may involve an application, credit review, income or asset documentation, and a decision timeline that varies by institution and customer. A watch-backed loan is secured by the watch; its availability and terms depend heavily on the collateral and the lender’s process.
Neither product is inherently better. A bank line may have a lower borrowing cost or provide reusable access to credit. A watch-backed loan may be more practical when the borrower needs a one-time amount on a short timeline, values discretion, or does not want to pursue a broader credit application.
Why Privacy Can Be Worth Paying For
“Privacy” does not mean no records, no questions, or no legal obligations. A reputable lender needs to verify the collateral and document the transaction. The meaningful distinction is often about what information is relevant to the loan, who handles it, and whether the borrower has to open up a wider financial picture to access the funds.
A focused collateral review
With a watch-backed loan, the process centers on the watch: what it is, whether it is authentic, its condition, whether key components are correct, and how readily it can be sold if necessary. The lender may still request identity and transaction information, but the underwriting focus is the asset rather than a full review of the borrower’s household finances.
For an owner who is comfortable pledging a valuable watch but prefers not to pursue a general-purpose loan, that distinction matters. It can also feel more contained: the borrower is discussing one item and one transaction rather than explaining the purpose of a purchase or sharing a broader financial narrative.
Discretion around a time-sensitive purchase
Some buyers do not want a public or extended process around a purchase. At a major collector event, a vehicle opportunity may appear with little notice. Others may need cash for a business payment, a property expense, or a temporary gap between incoming and outgoing funds. In those situations, the owner may value a direct, private conversation and a defined collateral process.
Privacy is personal, though. Ask how the lender handles records, communications, custody, and information sharing. Read the agreement. Do not assume that a transaction is anonymous or that confidentiality has no limits.
Rolex as a Liquid Luxury Asset
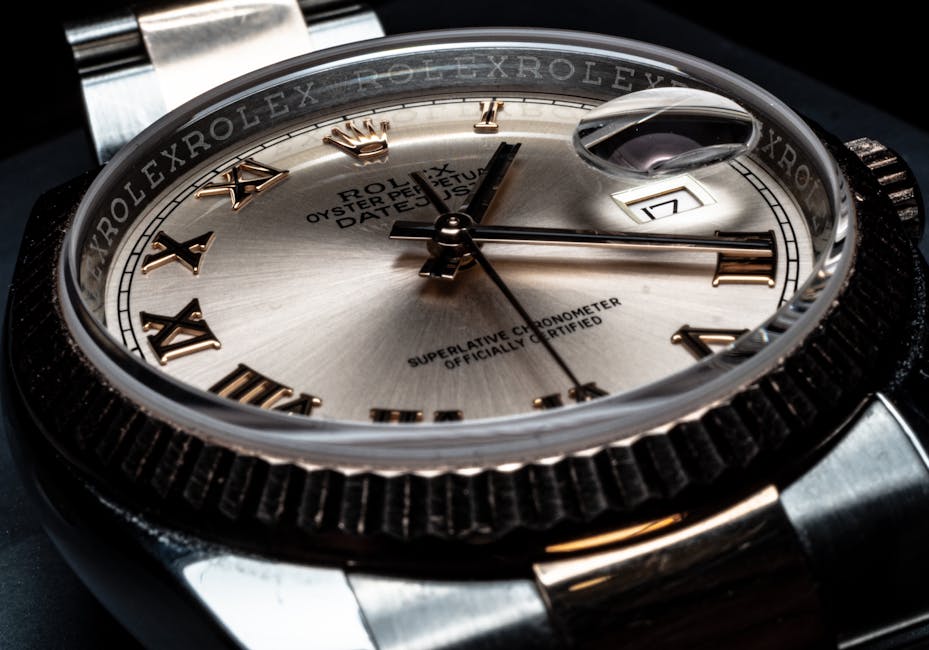
Rolex is often considered a liquid luxury asset because many models have broad recognition and an established secondary market. That does not mean every Rolex is easy to borrow against, or that any particular model will command a predictable amount. Liquidity depends on the exact reference, condition, originality, completeness, demand, and the terms a lender is willing to offer.
“Rolex” alone is not a valuation. A stainless-steel sports model with strong demand may be assessed differently from a less sought-after reference, a heavily polished watch, or one missing important components. Box and papers can matter, but they do not replace authentication and a condition review. Market demand can also change.
For owners, the advantage is that a recognized watch may be usable as collateral without being sold outright. They can seek short-term liquidity while retaining the possibility of getting the watch back after satisfying the loan terms. That is different from a sale, where the owner gives up the asset and any future use or resale decision.
There is an important caution: a liquid asset is not the same as cash. The amount a lender advances may be below a retail asking price or an optimistic online listing. The lender has to account for resale timing, costs, uncertainty, and the risk that the watch will not sell at an assumed price.
How Pricing and Authentication Shape the Offer
A sensible offer starts with evidence, not a vague promise of “top dollar.” Publicly tracked global secondary market pricing can help establish context: recent market activity, comparable references, and the difference between asking prices and actual transaction data where that data is available. Public pricing is a reference point, not a guaranteed loan value.
The watch itself then needs an authentication and valuation process. Depending on the item and the lender’s procedures, that may include checking the reference and serial information, examining the movement and components, assessing condition and originality, reviewing service history or documentation, and considering whether the watch is complete. The lender should explain what it checks and what could change the initial estimate.
Ask for a clear breakdown of the offer and the loan cost. “The rate is competitive” is not enough. You need to know the amount advanced, interest calculation, any fees, the term, payment schedule, renewal or extension terms, and the total amount required to redeem the watch on a specific date.
Question Why it matters How was the watch authenticated and valued? It shows whether the offer reflects the actual reference, condition, and marketability—not just a broad brand label. What is the total payoff on my planned repayment date? A rate alone does not show the dollars you will owe over the period you expect to borrow. What fees or extension terms apply? A short loan can become expensive if it runs longer than planned or is renewed. How is the watch stored and insured? The collateral remains your property subject to the agreement, so custody terms deserve attention. What happens if I miss a deadline? Understand notice periods, default provisions, and the process for resolving an unpaid loan before you sign.
The Rate-versus-Privacy Tradeoff
Here is the tradeoff. A watch-backed loan may cost more than a lower-rate bank product, but the borrower may value a faster, more focused process and less exposure of broader financial details. Whether that premium is reasonable depends on the actual loan terms and the value of acting now.
Compare the dollar cost over the expected borrowing period, not just the advertised annual rate. If you need funds for a few weeks, calculate the payoff for those weeks, including applicable fees. Then compare that amount with the cost and timeline of a bank line of credit, a sale, or another source of cash.
Also ask what delay would cost. If a time-sensitive purchase disappears, does waiting have a real consequence, or is urgency pushing you into an unnecessary expense? A Friday-night decision before an auction can feel immediate. It is still worth taking the time to understand the contract and confirm that repayment is realistic.
For a longer borrowing period, a lower-rate credit line may be more economical if you qualify and can access it in time. For a short, defined cash gap, a watch-backed loan may be worth considering if the borrower values speed, discretion, and keeping the watch rather than selling it. The best comparison is between real offers, with real dates and total costs.
Auction-Week Timing and Planning
Events at WestWorld of Scottsdale draw buyers, sellers, and collectors who may need to make decisions on a schedule. Barrett-Jackson can create a concentrated moment: a desired car is approaching the block, travel and bidding plans are already in place, and other funds may not be available until later. That is precisely when financing should be arranged before the pressure peaks.
If you are considering a watch-backed loan around auction week, start before you are standing at the https://instaquoteapp.com/what-should-i-do-if-i-need-money-on-a-friday-night-before-bidding/ event. Ask what the lender needs to inspect the watch, how long its authentication and valuation process typically takes, when funds may be available, and whether the timing changes during busy periods. Do not assume a same-day decision or transfer unless the lender confirms it for your specific transaction.
Collectors who speak with firms such as Diamond Banc can ask about the firm’s current process, requirements, and loan terms directly. Compare those details with any bank line of credit alternative already available to you. The name of a lender does not replace a careful review of its written agreement.
A practical planning checklist
- Set the borrowing amount. Decide how much cash you actually need, rather than borrowing the maximum offered.
- Choose a realistic repayment date. Identify the funds you expect to use for repayment and when they are expected to arrive.
- Gather watch information. Note the reference, known service history, condition, and available box, papers, or receipts.
- Request the full terms. Get the advance amount, rate, fees, term, payoff calculation, extension rules, and default process in writing.
- Confirm logistics early. Ask about inspection, custody, insurance, communication, and funding timing before auction week.
- Keep a fallback plan. If the transaction takes longer than expected, know whether you can wait, use another source, or walk away.
When Choosing Privacy Over Rate May Make Sense
A watch-backed loan may be a reasonable option when the need is temporary, the repayment source is clear, and the owner would rather pledge the watch than sell it. It may also fit someone who values a contained collateral-based process and understands the cost of that convenience.
It is a weaker fit when repayment is uncertain, the loan may be renewed repeatedly, the borrower has a lower-cost source of funds available on the same timeline, or the watch has special personal value that makes the consequences of default unacceptable. In those cases, the rate is not the only issue. The risk of losing access to a meaningful asset deserves serious weight.
Do not treat a Rolex—or any watch—as an investment merely because it has a visible secondary market. Prices can move, and the market value is https://technivorz.com/barrett-jackson-bidders-do-they-really-use-watches-to-fund-purchases/ not the same as the cash a lender will advance today. The useful question is narrower: can this watch support a loan whose cost, timeline, and collateral terms fit a specific need?
The Bottom Line
People choose privacy over rate when the value of a focused process, short-term liquidity, or timing is worth the extra cost to them. A watch-backed loan can be a bank line of credit alternative for a defined need, but it is not the same product and should not be evaluated by rate alone.
Before pledging a watch, look at publicly tracked global secondary market pricing for context, understand the authentication and valuation process, and get the total payoff for your planned repayment date. Around an auction, make those decisions before the bidding starts. Speed is useful only when the terms are clear and the repayment plan is real.